People often tend to focus on the accumulation phase of investing. But the decumulation phase, when you’re spending down your assets, is often more problematical. Having an adviser with specialist expertise in retirement planning is hugely beneficial.
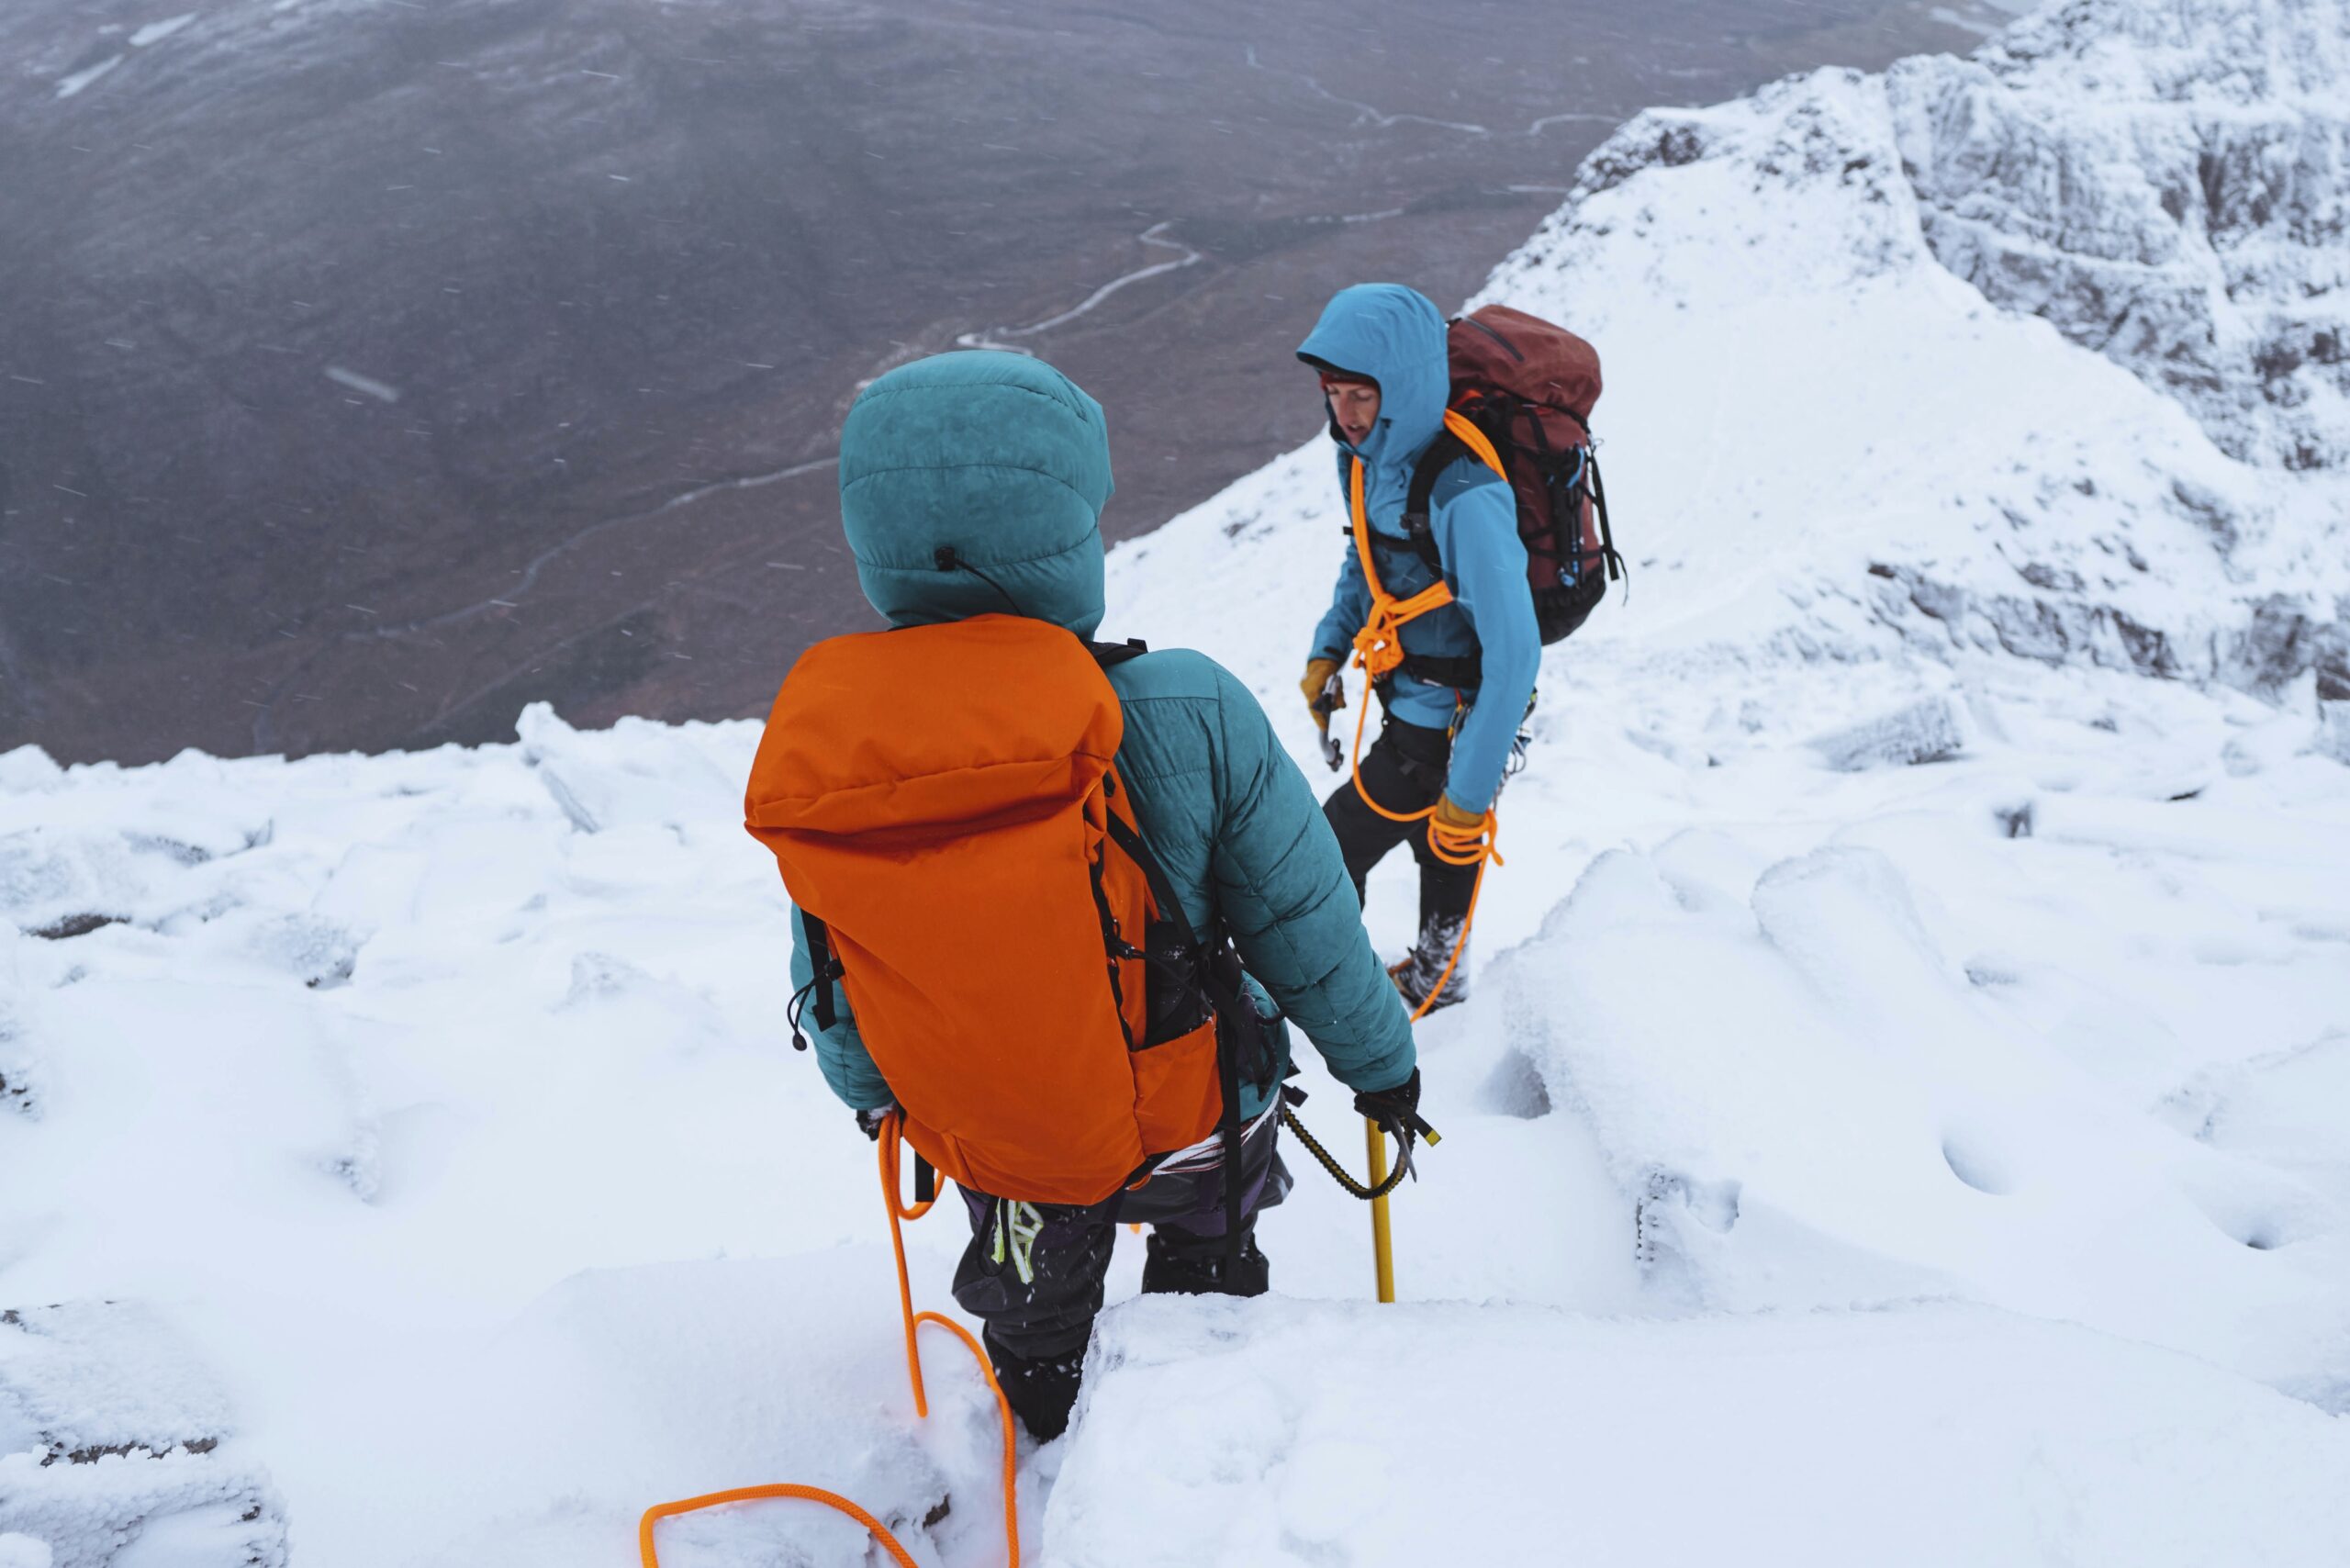
On the face of it, wealth management and mountain climbing may seem to have little in common, but there are several similarities between the two. Both require goal setting and long-term planning. To succeed at either you need to have endurance and persistence, but also adaptability to changing conditions. And, for the vast majority of people, both require expert help.
Another similarity is that wealth management and mountain climbing both involve risk. No matter how prepared you are, things don’t always going to plan, and factors beyond your control can soon put you in jeopardy.
An interesting fact about mountain climbing is that the risk tends to be greater on the way down a mountain than on the way up. Certainly, more accidents occur in the descent than the ascent. Again, it’s the same with investing. Although most of the focus tends to be on what we call the accumulation phase - in other words, building wealth in preparation for retirement - the decumulation, or drawdown, phase is much more challenging and, yes, potentially more dangerous.
Why dangers lurk in decumulation
This might seem like a dramatic thing to say, but it’s true. As long as you develop the right habits, invest your money sensibly and have a financial adviser who can help you to stay calm and rational in a bear market, the accumulation stage is relatively straightforward. You’re far more likely to come unstuck in decumulation, and there are several reasons why that is.
Stock market volatility
For most people under the age of 50, market downturns really aren’t an issue, because there is plenty of time for markets to recover. In fact most accumulation-phase investors benefit from volatility because it enables them to buy assets at lower prices. In decumulation, however, selling equities after prices have fallen to fund withdrawals can lock in losses and reduce the portfolio's potential for growth, making it harder to sustain withdrawals over a long retirement.
Sequence of returns risk
If an investor experiences significant market losses early in retirement while simultaneously withdrawing funds, it can severely diminish the portfolio’s ability to recover, even if the market later improves. Although there are things you can do to mitigate the negative impact of an unfavourable sequence of returns, it’s entirely down to an accident of birth or, more precisely, retirement age, whether or not you’re affected.
Inflation risk
Inflation can severely erode your money’s purchasing power over time. During the accumulation phase, investors can adjust their contributions and investment choices to counteract inflation. In drawdown, though, inflation can affect the real value of regular withdrawals, potentially requiring higher withdrawals to maintain the same standard of living, thereby accelerating the depletion of the portfolio.
Longevity risk
One of the great unknowns faced by those in decumulation is how long they’re going to live for. Depending on the size of your retirement pot, the risk of outliving your savings, known as longevity risk, can be substantial. Misjudging how long you will need to depend on those savings can put you in danger of running out of money in your final years.
Less flexibility to earn and save
During the accumulation phase, you can increase the amount you invest in your pension, or else do extra work, to improve your financial situation. In the drawdown phase, however, there may be fewer opportunities to earn additional income. You may also be less willing to go back to work if you haven’t been earning for several years.
Emotional and psychological factors
Retirement requires a change of mindset. Until that point, the focus is on saving and investing; but once you finish work, you need to turn your attention to spending down their assets. This might seem like “a nice problem to have”, but many retirees struggle, emotionally and psychologically, with this change of emphasis. Without professional advice, it’s easy to make poor financial decisions, like withdrawing too much money too early in retirement.
Seek professional advice
What these dangers underline, more than anything, is the importance of seeking professional financial advice. Good advice is valuable at every stage of your investing journey, but in the run-up to retirement and the years immediately following it, having an adviser really is essential.
rockwealth partner Tim Horrock's points to research by the free guidance provider Pension Wise, published in December 2022, as evidence of the value of seeking help with decumulation.
“The research revealed that 36 per cent of those who did not consult Pension Wise had spent pension savings on discretionary items such as holidays or a new car, compared to just 14 per cent of those who had received guidance,” says Tim.
“Those who had used Pension Wise were also more likely to reinvest their money or pay off loans or mortgages. What is particularly noteworthy is that 23 per cent of these individuals said they had gone on to seek independent financial advice.”
There are, it’s true, some useful resources online for those approaching retirement. But Tim Horrock's cautions against complacency about the dangers of a DIY approach.
“Don’t be fooled by online retirement calculators,” Tim warns. “While they may be valuable for calculating cashflow projections, they are generally based on the false assumption that your expected rate of return will be the same each year. The real world doesn’t operate like this, now more so than ever.”
Another reason for consulting a firm, like rockwealth, with specific expertise in retirement planning is that the products available to those in decumulation are changing all the time. The last two years have seen a significant shift towards annuities and other guaranteed income products, which were out of favour for many years while interest rates were low. For Tim Horrock, these sorts of products may be suitable for some.
“There is a strong argument for a mix-and- match approach to providing for your income needs in retirement, and guaranteed income products might sensibly be used to ensure that essential spending is covered,” says Tim.
"Many clients cover their essential expenditure with a mixture of State Pension and, for the lucky few), workplace pensions. For those clients who don’t have enough, they could buy an annuity to make good the shortfall. There is no need to annuitise the whole portfolio, just enough to cover the shortfall."
As ever, the right approach or combination of approaches will be unique. Every person is different, and retirement needs will not be the same as the next person, which is why it’s important not to apply a one-size-fits-all solution to managing retirement wealth.
APPROACHING RETIREMENT?
Are you thinking about retirement in the next couple of years? Or have you recently retired?
Either way, it’s vitally important to seek help from a financially adviser who really understands the complexities of the drawdown phase and the risks involved.
Why not give us a call or send us a message? We would be happy to have an exploratory meeting with you, with no obligation.
© rockwealth MMXXIV