Pension Advice in Norwich
Know what you hold.
Choose what comes next.
Understand each pension’s costs, benefits and restrictions before you transfer, contribute or begin taking retirement income.
Start with what the pension needs to do for you
A pension is more than an account to organise. It may hold valuable guarantees, provide future income, offer tax advantages and create choices for your beneficiaries. Once lost, some of those features cannot be recovered.
We begin by establishing what each arrangement provides, what it costs, how it is invested and which restrictions apply. This creates a reliable starting point before considering consolidation, additional contributions or withdrawals.
We then connect each pension to the decision in front of you. When retirement is approaching, cashflow modelling can indicate when benefits may be needed and how they interact with savings, ISAs, State Pension and expenditure. Earlier in life, the focus may instead be contribution levels, tax relief and investment strategy.
Any recommendation sits within your wider Financial MasterPlan rather than treating the pension in isolation. This allows us to balance tax with access, investment risk with timescale and potential inheritance benefits with the need to fund your own future.
Where pension assets stay invested, we use the same patient, diversified principles that underpin our evidence-led investment advice. We do not pretend pension decisions are simple. Our role is to explain the parts that matter so you can make an informed choice.
Important pension choices deserve more than a quick comparison
Combining arrangements may be convenient, but simplicity is only part of the decision. We compare charges, investment choices, access rules and valuable protected features before recommending whether anything should change.
Understanding the Pensions You Hold
Drawing a pension involves choices about tax-free cash, taxable income and continuing investment risk. We assess those options alongside your other assets and the expenditure your retirement plan is intended to fund.
Deciding How to Access Benefits
Questions worth answering before you act
Should I automatically combine old pensions?
No. One plan can be easier to administer, but transferring could mean losing guaranteed annuity rates, protected tax-free cash, a favourable pension age or other benefits. We compare the existing arrangements with what a new plan would offer, including charges and investment choice, before judging whether consolidation supports your wider Financial MasterPlan.
What should I understand before accessing a pension?
Taking benefits can affect income tax, future contribution allowances and how long the remaining fund might last. Before withdrawing, it helps to clarify the purpose of the money, which other assets are available and how the decision fits your plan for retirement income. The normal minimum pension age is due to rise from 55 to 57 in April 2028, although individual protections can differ.
Could making pension contributions reduce tax?
Potentially. Personal and employer contributions may qualify for tax relief, but the amount available depends on earnings, annual allowance rules, earlier funding and whether benefits have already been accessed flexibly. We consider contributions alongside your need for accessible cash and other allowances, rather than treating tax relief alone as a reason to pay more in. See the official GOV.UK guidance for current rules.
Where does the State Pension fit into my plan?
The State Pension can form an important foundation, but it often starts later than the age at which people hope to leave work. We include your forecast and expected start date in the cashflow plan to show what private pensions and other assets may need to provide before and after it begins. Any gaps or decisions about voluntary contributions should be checked against your individual National Insurance record.
Visit us in Norwich
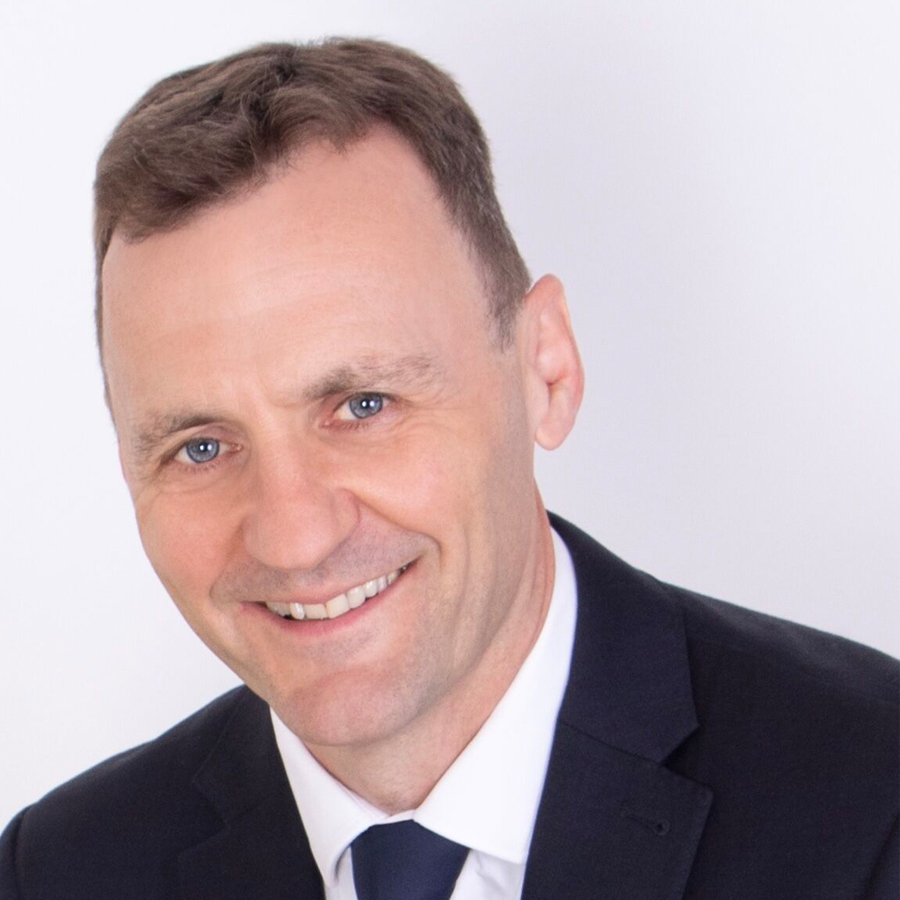
Meet Matt Frary at St Georges Works, 51 Colegate in Norwich, or arrange an online meeting if that is more convenient. We advise clients across Norwich and Norfolk who want to understand the consequences before making an important pension decision.
rockwealth Norwich IFA
St Georges Works, 51 Colegate, Norwich, NR3 1DD
Start with the question that is on your mind
You do not need to arrive with everything organised. Tell us what has changed, what feels uncertain or what you want life to look like next. We will explain whether our Norwich team can help and what the next step would involve.